Prerequisite: Spot, CFDs and futures are different contracts
On a small screen, scroll the figure sideways or open it full size.
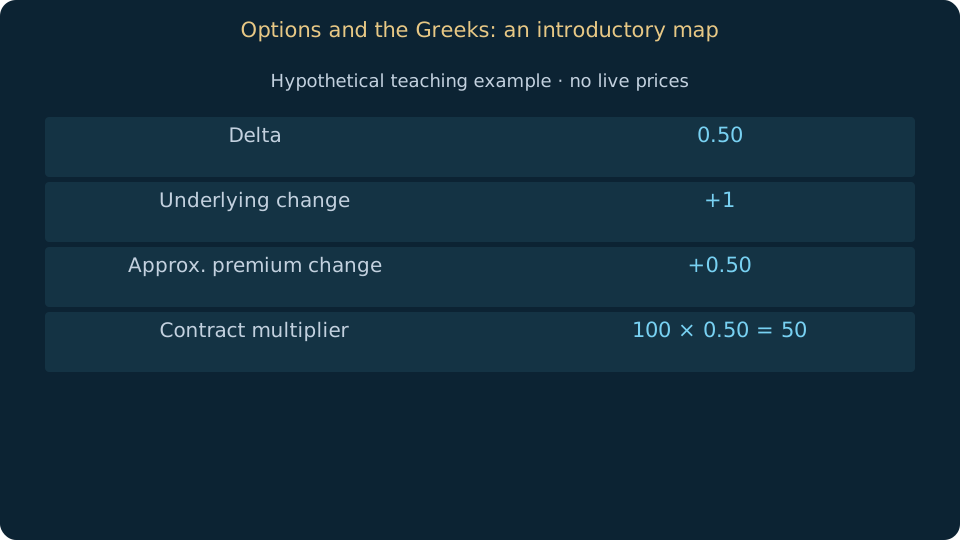
Read the figure
Delta is a local approximation with other inputs fixed. Gamma, volatility and time can change the realised option result.
Learning objective
Explain delta, gamma, theta and vega as model sensitivities rather than promises.
An option buyer pays a premium for defined rights under its contract; calls and puts differ in direction, and exercise style and settlement vary. An option seller has corresponding obligations. Some uncovered short option positions can have very large or theoretically unlimited losses; do not generalise the buyer’s premium limit to the seller.
Delta estimates local price sensitivity to the underlying; gamma describes how delta changes. Theta estimates sensitivity to time passage, while vega measures sensitivity to implied volatility. Their units and conventions depend on the platform, and their values change as price, time and volatility change.
An option can lose value even when the underlying moves in the expected direction if time decay or volatility changes dominate. Greeks are local model approximations, not exact predictions for large jumps. Check contract multiplier, expiration, liquidity and exercise consequences before evaluating a hypothetical payoff.
Worked example
For a hypothetical option with delta 0.50, a one-unit underlying increase suggests roughly a 0.50-unit premium increase if other variables remain fixed. A multiplier of 100 makes that approximately 50 per contract; gamma and changing volatility can alter the actual result.
Common mistakes
Do not treat delta as a guaranteed probability of profit. Check whether vega refers to one percentage-point volatility change.
Practice
For one hypothetical call, sketch expiry payoff and separately explain what delta, theta and vega would measure before expiry.
Sources & further reading
Saved on this device. Export a backup before clearing browser data or changing device.
My learning pathEditorial review: 15 October 2026 · AI-assisted technical review; independent specialist review pending.
Translation available · editorial review pending